
Housing in the Spotlight: National Australia Bank CEO Flags Australia’s “Biggest Societal and Policy Challenge”

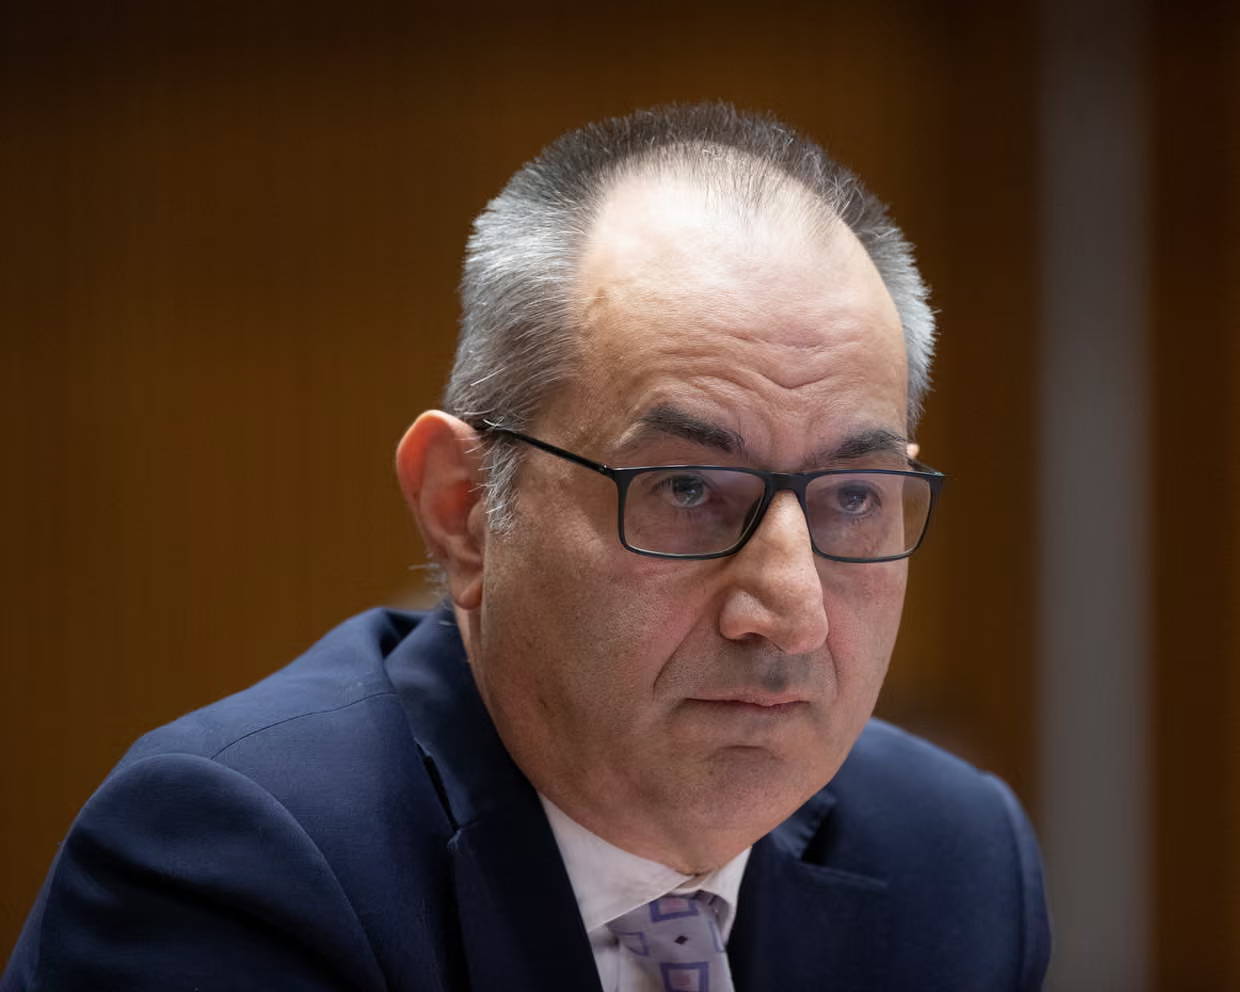
In a striking declaration, Andrew Irvine—the Chief Executive Officer of Australia’s major lender National Australia Bank (NAB)—said that housing represents the country’s “biggest societal and policy challenge”.
The comments, alongside the bank’s annual results, underline both the gravity of Australia’s housing situation and a growing willingness of business leaders to intervene directly in public policy debates.
The Context: A Bank with Skin in the Game
NAB posted a cash profit of A$7.09 billion (≈US$4.6 billion) for the year to 30 September 2025, only marginally below the prior year and slightly under analysts’ expectations.
That performance came amid rising business lending and deposit growth—but also cost pressures and increased impairment charges. Housing matters to NAB because the home‑loan business is central to its operations; a healthy housing market underpins both mortgage demand and broader economic momentum.
Against this backdrop, Irvine’s open letter to customers, policy makers, and developers declared NAB’s ambition to lend at least A$60 billion over the next five years to help ease the housing shortfall.
Why Housing Is at the Forefront
Irvine pointed to a number of structural factors behind his stark assessment:
Shortfall in supply: Australia is on track to fall well short of its target of building 1.2 million homes by 2029, with construction levels near decade lows.
Regulatory and process bottlenecks: Approvals, zoning, infrastructure coordination, and skilled labour constraints are usually cited as the reasons homes are not getting built fast enough.
Wider economic and social consequences: The high cost of housing and the lack of access to property markets weigh on younger generations, first‑home buyers and renters, making housing not just an issue of property but one of fairness, opportunity and productivity.
Irvine went further: “What we need to do now is really driving productivity, more reliable energy, more dwellings, less rules, quicker decisions of what this country needs to grow faster without generating inflation.”
NAB’s Proposed Response
NAB has outlined a dual‑track approach to meet the housing challenge:
Supply side: A$30 billion earmarked for financing residential‑focused commercial real estate development, including build‑to‑rent, student accommodation and community housing.
Demand side: A further A$30 billion allocated to assisting first‑home buyers, through programs like the government’s 5 % Deposit Scheme.
NAB estimates this could support around 55,000 first‑home buyer loans and facilitate approximately 50,000 new dwellings.
The bank also signalled its willingness to tap third‑party institutional capital—via superannuation funds, sovereign wealth funds and other co‑investment vehicles—to scale impact.
The Implications: For Business, Policy and Society
Business leaders stepping into policy: Irvine’s comments reflect a broader trend of corporate executives engaging in the national policy discourse. His statement moves housing from an industry‑specific risk to a national strategic issue.
Housing as a productivity lever: Because NAB is linking housing supply to productivity and economic potential, framing the issue as one not only of social welfare but as foundational to growth-challenging governments and regulators to respond accordingly.
A test of public‑private collaboration: NAB’s A$60 billion commitment signals that the private sector expects to play a major role but also positions complex regulatory and systemic barriers as shared responsibility.
Investor and market signals: With lenders actively endorsing housing supply as a policy priority, financial markets and property participants will increasingly monitor approvals, construction pipelines, and regulatory reform as leading indicators for risk and opportunity. Challenges and Risks Ahead After bold framing and commitments, several important challenges persist: Large-scale financing does not automatically translate into many more homes; labour shortages, materials inflation, and planning delays remain stubborn.
First-home buyer support programs need to be carefully balanced so they do not exacerbate price inflation by simply increasing demand without matching supply. The political and regulatory fragmentation across states and territories means that national targets could prove difficult to coordinate and deliver. Because banks have exposure to housing, as NAB’s own results show, they are vulnerable to turns in the real‑estate cycle-so overreliance on property without diversification poses risk.
Conclusion By declaring housing to be Australia’s “biggest societal and policy challenge,” Andrew Irvine has put the issue at the heart of his bank’s strategic agenda-and at the center of broader national debate. The scale of ambition is underlined by NAB’s proposed A$60 billion lending initiative, but the success of this will depend on far more than capital-it requires reform, innovation and cooperation across government, industry and the community. For a magazine that focuses on leadership and impact, his statement provides a compelling moment: business not only recognising a national problem, but committing to be part of its solution.