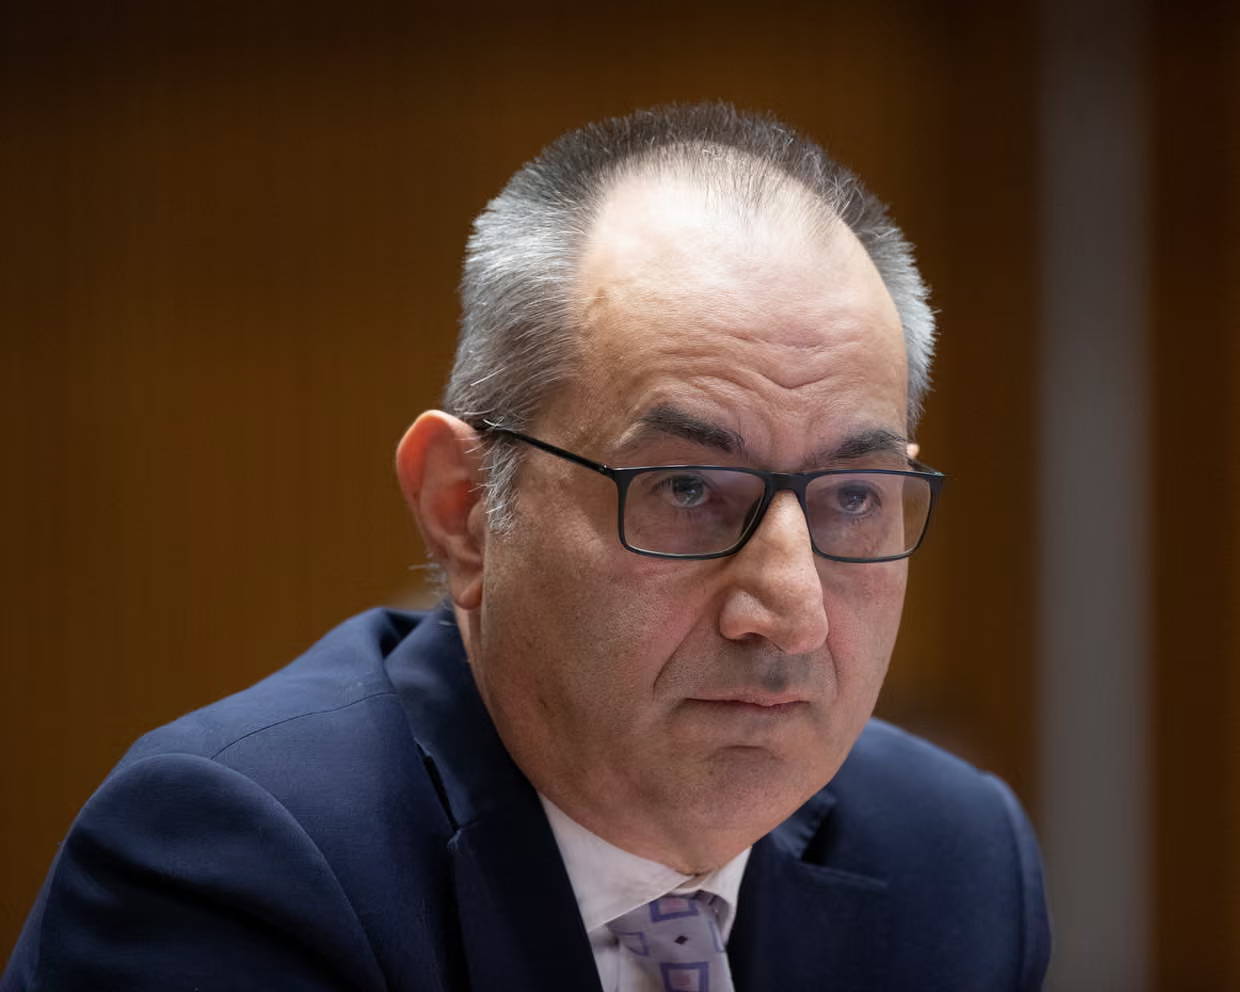


ANZ is in a critical period of transformation under the leadership of its Chief Executive Officer Nuno Matos, who has taken over early in 2025. At a time when the bank is dealing with weakening margins, changing economic fortunes, and growing competition, he has taken steps to position ANZ for resilience, simplification, and long-term growth. His strategic roadmap, outlined in its latest annual results briefing, heralds a new drive for operational efficiency, customer-oriented reforms, and disciplined cost management.
ANZ reported a 14% decline in annual cash profit, a result driven by higher funding costs, a one-off regulatory charge, and sustained pressure on net interest margins. The announcement came at a time when Australian banks are experiencing slower credit expansion and increasing competition from nonbank lenders as well as digital-first financial platforms. While the result reflects a broader industry trend, Matos has highlighted the need for the bank to tackle the structural pressures head-on rather than wait for market conditions to shift.
Speaking to analysts and investors, the chief executive acknowledged the challenges but kept a forward-looking stance. “We cannot rely on external conditions improving,” he said. “The bank must act decisively to simplify itself, improve its cost base, and position for growth.” In light of this, ANZ is targeting a three percent reduction in total costs in FY26, moves that will include streamlining internal processes, reviewing supplier arrangements, and accelerating digital transformation across operations.
It is complemented by the “ANZ 2030 strategy”, which is a long-term plan structured around four guiding pillars: Customer First, Simplicity, Resilience, and Delivering Value. The initial two-year cycle, covering FY26 and FY27, will build a more solid foundation for the bank. This includes further strengthening the technology base, boosting risk management, and fundamentally changing the way that customers interact with the bank. The phase starting in 2028 is designed to position ANZ for growth with an expanded product suite and increased market share across retail banking, commercial services, and institutional finance.
One of the areas getting immediate attention is the customer experience, where Matos tries to eliminate frictions and modernize the service interactions. The bank intends to simplify product suites, enhance digital onboarding tools, and ensure more responsive support systems. Matos has made it clear that if ANZ is to earn loyalty in fiercely competitive banking, then trust and ease of doing business should be at the heart of its identity.
At the same time, Matos has emphasized operational resilience as a non-negotiable premise for any business. Sufficient capital, disciplined risk management, and thorough balance sheet allocation will support this journey of transformation. The bank’s institutional business has remained a source of critical revenue, especially from cross-border and trade finance, and Matos is likely to continue developing ANZ’s presence in the Asia-Pacific markets.
Importantly, Matos has been realistic about the time horizon required for meaningful results. Shareholders seeking quick returns have been reminded that this is a multi-year journey. However, the bank’s leadership has stressed the fact that the changes being introduced are designed to make sure the bank is more agile, more focused, and better positioned to deliver stable returns despite macroeconomic uncertainty.
Attention has also turned to Matos’ leadership style. Given his reputation for strategic clarity and leading complex reorganizations from previous senior banking positions in international markets, he has been described as a calm, thoughtful, and deeply data-driven leader. At ANZ, this means a process-oriented approach that emphasizes sequenced reform and strong communication to employees, investors, and customers alike.
But the big challenges are still ahead. Margin compression continues to squeeze the bank’s retail operations, while fintech upstarts redefine customer expectations. Economic indicators such as moderating inflation and increasing lending rates may also affect credit demand. Yet Matos seems ready to meet the new realities rather than be defined by them. “The journey we are on is not about quick fixes. It’s about building a bank that is simpler, stronger, and positioned to serve customers and communities for the long run.” As ANZ navigates this transition, the world will indeed be watching to see how deftly Matos can balance cost discipline with innovation, stability with growth. The result will be important, not only to ANZ’s future, but also potentially as any blueprint for how legacy financial institutions adapt in an increasingly digital, globally competitive banking environment.